Macro at a Glance
Saudi Arabia and Pakistan established a mutual defence agreement on September 17, marking a significant shift in regional security dynamics. This formal pact treats attacks on either nation as collective threats, representing an unusual security guarantee for the Gulf region. The move occurs amid concerns about U.S. commitment to the area and follows Israeli military operations targeting Qatar. While ambiguous in its specific language, the agreement carries substantial symbolic weight—Saudi Arabia now anchors part of its deterrence capabilities to Pakistan, the sole Muslim-majority nuclear power. This development has prompted extensive discussion regarding potential implicit nuclear assurances, according to market observers. Markets view this through dual lenses: near-term stabilization of energy infrastructure security, coupled with heightened systemic risks should Iran, India, or Israel engage either signatory. (Reuters, Bloomberg, FT)
The Federal Reserve implemented a quarter-point interest rate reduction on September 17. Governor Stephen Miran dissented, advocating for larger cuts. Simultaneously, efforts to remove Federal Reserve official Lisa Cook have triggered concerns about executive interference in monetary policy independence and potential political manipulation of financial decision-making. (FT)
France experienced a credit rating downgrade from Fitch, moving from "AA-" to "A+"—the lowest rating ever assigned by major rating agencies. The nation carries debt equivalent to 115.6% of GDP as of Q2. Conversely, Portugal received an upgrade from "A" to "A+". Moody's and S&P are expected to announce their French assessments during October-November. (Bloomberg, Le Monde)
One Sector, One Insight
Basic Materials and Energy
Anglo American (AAL.L) continues executing its strategy to divest its 85% De Beers stake. Following substantial asset write-downs and natural diamond market contraction, the company prioritizes commercial sale options. Interest from potential buyers is intensifying: Botswana aims to acquire majority control by month-end October, while Angola's Endiama submitted a fully-financed minority stake proposal. This reflects producing nations' determination to shape De Beers' direction. Anglo reports "serious buyers" accessing information systems, with resolution anticipated within 6-9 months. An alternative 2026 IPO remains possible if commercial negotiations falter. Proceeds (approximately $4.9 billion book value) would allow Anglo to concentrate on copper and iron ore. Prospective De Beers ownership relies on disciplined supply management and Chinese demand recovery to counterbalance synthetic diamond competition. (FT, Reuters)
Consumption and General Public Services
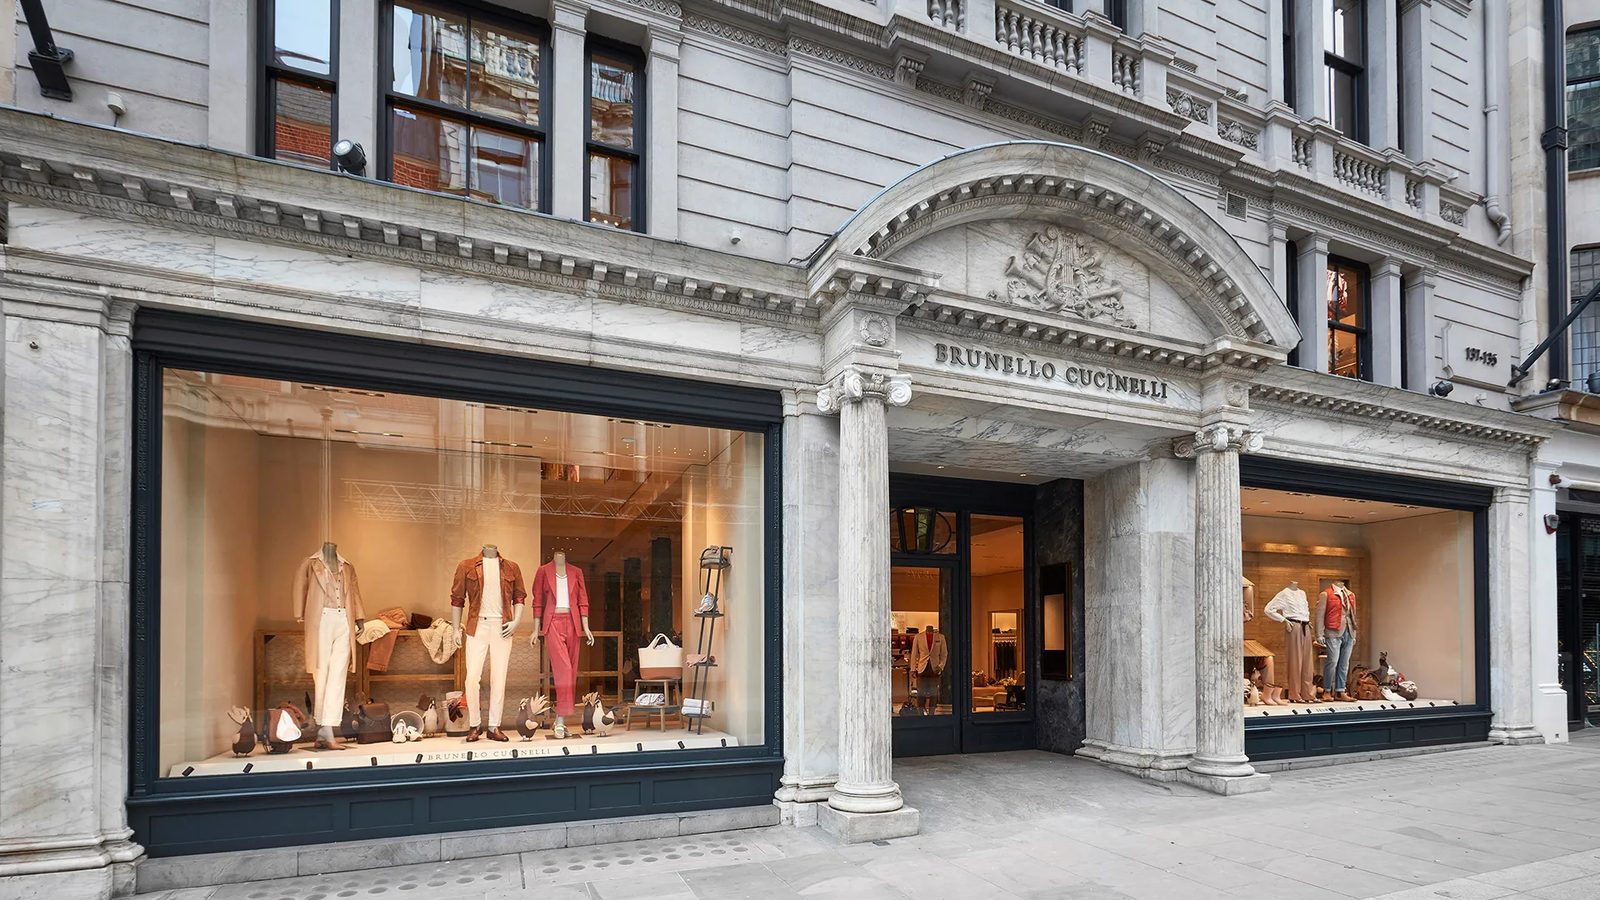
Brunello Cucinelli (BC.MI) shares experienced their steepest historical decline following Morpheus Research's critical report accusing management of shareholder deception and EU sanctions violations. The stock plummeted over 17%, triggering temporary Milan exchange suspension. Allegations include continued Moscow boutique operations and Russian sales despite post-2022 invasion sanctions. Morpheus additionally claims the company employs aggressive discounting via off-price channels, potentially compromising its luxury brand positioning. Cucinelli characterized the report as "defaming" and announced legal defense preparations. (Reuters, Morpheus Research)
Financial Services
The private equity sector faces notable deceleration following an extended growth period. A fundamental cash-flow problem threatens momentum. Private equity prospered during low-rate conditions enabling leveraged acquisitions and inflated valuations. Current elevated rates have escalated capital costs, reducing deal attractiveness and exit profitability. Portfolio companies remain unsold, creating an "exit logjam." Limited partners (investors) express growing frustration. (Bloomberg, Private Equity Wire)
Healthcare
Roche (ROG.SW) committed to acquiring U.S. biotech 89bio for approximately $3.5 billion, strengthening positions in metabolic, renal, and cardiovascular therapeutics. Simultaneously, Pfizer (PFE) is acquiring biotech Metsera for up to $7.3 billion (including milestone payments), signaling renewed obesity and metabolic disease treatment focus. These transactions exemplify healthcare sector consolidation momentum, particularly as major pharmaceutical corporations pursue next-generation assets. (Reuters, FT)
Industrials
Jaguar Land Rover gradually restored operations following late-August cyberattacks that disabled IT infrastructure and shuttered three British facilities for approximately four weeks. Production and primary logistics/invoicing systems commenced phased restart after one of Europe's most disruptive automotive manufacturing incidents. The August 2 disclosure impacted the entire Midlands supply chain, costing tens of millions weekly through factory closures and staff furloughs. The UK government provided £1.5 billion export financing guarantees supporting supplier liquidity. JLR secured an additional £2 billion credit facility spanning 18 months from banking partnerships for recovery buffer support. Complete financial impact and attack circumstances remain undisclosed. (Reuters, The Guardian, FT)
Technology and Network Equipment
Electronic Arts (EA) finalized acquisition terms for $55 billion all-cash privatization—history's largest sponsor-led cash buyout. A consortium including private equity firm Silver Lake, Saudi Arabia's Public Investment Fund, and Affinity Partners (founded by Trump's son-in-law) will pay $210 per share—representing 25% premium versus pre-announcement pricing. This reflects substantial gaming industry consolidation. Privatization permits EA (publisher of Madden NFL, Battlefield, The Sims franchises) to pursue extended-term strategic development without quarterly performance pressures. (Reuters, EA News)
The Stock of the Month
Andean Precious Metals Corp. (APM.TO) achieved approximately 47% September performance, among market leaders. Growth stemmed from historic gold rallying establishing record highs. The Canadian enterprise holding Bolivian and Californian silver/gold deposits participates in junior mining momentum accompanying precious metals surge. Gold has appreciated 47% year-to-date, driven by Federal Reserve deep-cut expectations and intense safety-driven investing amid worldwide instability. (Yahoo Finance, Reuters)
Key Performances
| Index/Asset | September 30 Close | Monthly Change | Year-to-Date |
|---|---|---|---|
| S&P 500 | 6688.46 | +3.53% | +13.72% |
| Dow Jones | 46397.89 | +1.87% | +9.06% |
| NASDAQ | 22660.01 | +5.61% | +17.34% |
| FTSE 100 | 9350.43 | +1.78% | +14.41% |
| CAC 40 | 7895.94 | +2.49% | +6.98% |
| DAX | 23880.72 | -0.09% | +19.95% |
| SMI 20 | 12109.42 | -0.64% | +4.38% |
| MSCI World | 4305.10 | +2.65% | +15.66% |
| VIX | 16.26 | +5.99% | -6.17% |
| CHF/USD | 1.2552 | +0.41% | +13.85% |
| CHF/EUR | 1.0695 | +0.06% | +0.39% |
| Brent Crude | $66.12/bbl | -0.99% | -10.82% |
| Gold Spot | $3882.70/oz | +11.77% | +48.98% |
Upcoming Events
- October 15: US CPI Release
- October 26: ECB Governing Council Meeting
- October 28-29: FOMC Meeting