Macro at a Glance
U.S. Treasury yields have increased substantially since early October despite the Federal Reserve's pivot toward rate reductions. The surge stems from mounting national debt and electoral uncertainty. With the debt-to-GDP ratio projected to surpass 100% and approximately $9 trillion in obligations requiring refinancing annually, Treasury issuance volumes are expected to rise by roughly 30%. Political factors introduce additional market turbulence, as different administrations could pursue vastly different fiscal approaches—from substantial social spending expansion to unpredictable, inflation-prone policies.
Germany's economy contracted 0.2% this year following a 0.3% decline in 2023. Structural headwinds persist within critical sectors including automotive and chemicals. Volkswagen announced plant closures within Germany, while BASF signaled potential dividend reductions for coming years. The ruling coalition faces viability questions amid these economic pressures.
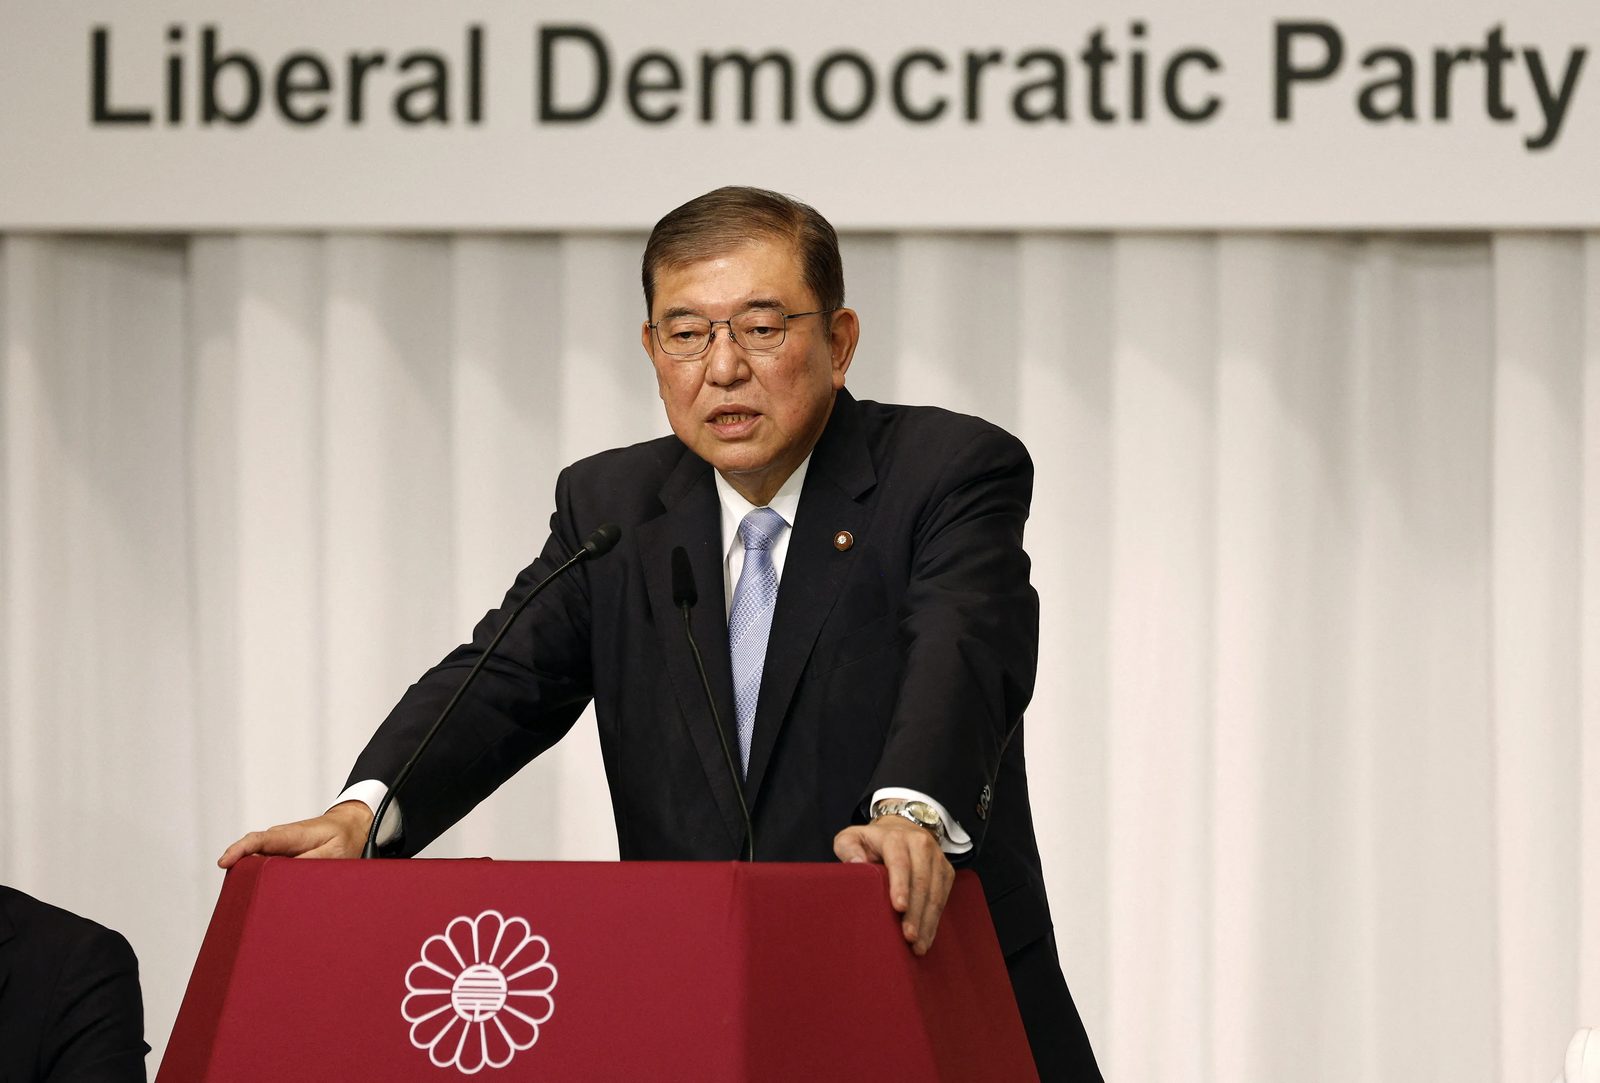
Japan's Prime Minister Shigeru Ishiba, taking office October 1, called snap parliamentary elections to solidify his party's standing. The October 27 elections delivered a significant setback for the Liberal Democratic Party, which lost its parliamentary majority for the first time since 2009. This outcome threatens political stability, evidenced by currency depreciation immediately following the electoral results.
At the October BRICS summit, India and China reached territorial agreement regarding Himalayan disputes, with China making significant concessions. This diplomatic victory for India's government exemplifies declining American geopolitical influence. China's retreat appears strategically calculated—potentially freeing military resources to concentrate on Taiwan, suggesting a possible gradual blockade strategy rather than direct military confrontation.
One Sector, One Insight
Basic Materials and Energy
Oil surged over 8% due to escalating Middle Eastern tensions following Iran's strikes on Israel. Concerns about regional supply disruptions propelled Brent crude prices upward, though U.S. diplomatic efforts provided some moderation. Ongoing infrastructure threats maintain volatile pricing dynamics.
Consumption and General Public Services
McDonald's experienced significant turbulence when health authorities linked an E. coli outbreak across ten states to the company's hamburgers, causing share price declines of approximately 10% in after-hours trading. Despite withdrawing affected products, quarterly results released October 29 showed mixed performance: sales increased 3% to $6.9 billion, yet net profit declined 3% to $2.26 billion.
Financial Services
Hurricane Milton struck Florida on October 9, inflicting approximately €60 billion in damages and creating substantial reinsurance market volatility. Initial declines reversed when the hurricane downgraded to Category 3, allowing markets to price in increased premium expectations for subsequent years.
Healthcare
Sanofi announced October 11 that it was exploring divestment of its Opella consumer medicines subsidiary. After competitive bidding, American CD&R secured the asset for €16 billion on October 21. Concerned about production relocation, France's Public Investment Bank acquired a 2% stake and board representation to maintain domestic manufacturing.
Industrials
Tesla's third-quarter earnings surpassed expectations with $0.72 earnings per share against forecasted $0.58, though revenue of $25.18 billion slightly underperformed projections. Management projected 20-30% vehicle delivery growth for the following year, highlighting autonomous advancements and lower-cost model development.
Technology and Network Equipment
ASML disclosed results October 15 (due to technical error, released during trading rather than after-hours), revealing net bookings of €2.6 billion—approximately 50% below investor expectations. The semiconductor equipment leader reduced its 2025 revenue guidance to €30-35 billion from €40 billion previously, citing cautious customer expenditure and slower recovery outside artificial intelligence sectors. This announcement triggered broader semiconductor index declines exceeding 5%.
The Stock of the Month
Trump Media & Technology Group shares appreciated 139% during October, elevating company valuation to $7 billion. Wall Street employs this stock as a Trump electoral probability indicator. Notably, Truth Social posted second-quarter losses of $16 million against sales below $1 million, illustrating the company's limited commercial performance despite share appreciation.
Key Performances
| Index/Asset | October 31 Close | Monthly Change | Year-to-Date |
|---|---|---|---|
| S&P 500 | 5705.45 | -0.06% | 20.30% |
| Dow Jones | 41763.46 | -0.93% | 10.73% |
| NASDAQ | 18095.15 | 1.03% | 22.55% |
| FTSE 100 | 8110.10 | -1.50% | 5.58% |
| CAC 40 | 7350.37 | -2.46% | -1.90% |
| DAX | 19077.54 | -0.37% | 14.15% |
| SMI 20 | 11873.79 | -1.76% | 6.30% |
| MSCI World | 3647.14 | -1.30% | 15.04% |
| VIX | 23.18 | 17.39% | 71.29% |
| CHF/USD | 1.1580 | -2.53% | -3.04% |
| CHF/EUR | 1.0639 | -0.65% | -1.42% |
| Brent Crude | 73.13 $/bbl | -0.58% | -3.64% |
| Gold | 2746.88 $/oz | 3.39% | 33.41% |
Upcoming Events
- November 1: U.S. Unemployment Rate
- November 5: U.S. Presidential Elections
- November 7: Federal Reserve Interest Rate Decision
- November 13: U.S. Inflation Rate
- November 27: Core PCE Price Index & FOMC Minutes