Macro at a Glance
Trump's mid-August meeting with Putin in Alaska concluded without achieving a ceasefire accord, despite the president's initial optimism. European officials and Ukrainian leadership subsequently convened at the White House to deliberate security arrangements, revealing disagreements regarding territorial concessions. Later in August, Trump's suggestion to deploy Chinese peacekeeping forces faced swift rejection from both Kyiv and European capitals due to China's established relationships with Moscow.
A significant institutional dispute has emerged following Trump's efforts to dismiss Federal Reserve Governor Lisa D. Cook. The governor challenged her removal through legal action, and a Washington federal judge conducted initial proceedings on August 29th without rendering a decision, potentially setting precedent regarding presidential authority over central bank officials.
UK government bond yields experienced upward pressure, with the 30-year gilt reaching 5.62%—approaching its April high and representing levels unseen since the 1990s. This development increases public debt servicing expenses and necessitates substantial fiscal adjustments from the government.
Argentine financial markets experienced significant volatility following allegations regarding potential corruption involving the president's sister. The national stock index declined 4 percent while the currency weakened approximately 3 percent. Despite these developments, macroeconomic conditions showed improvement compared to earlier in the year.
One Sector, One Insight
Basic Materials and Energy
Ørsted announced a substantial capital raise of approximately $9.4 billion following a U.S. government suspension of the Revolution Wind initiative. The energy company has encountered repeated setbacks in American markets, having previously terminated multiple offshore projects. Share valuations declined substantially following the announcement, with investor concerns focusing on execution capabilities and geopolitical risks.
Consumption and General Public Services
WH Smith disclosed an accounting discrepancy that had inflated North American profitability figures. Management subsequently revised profit guidance downward for the region, reducing expectations by approximately 55 percent. The accounting adjustment represented a considerable reputational challenge for the travel retailer.
Financial Services
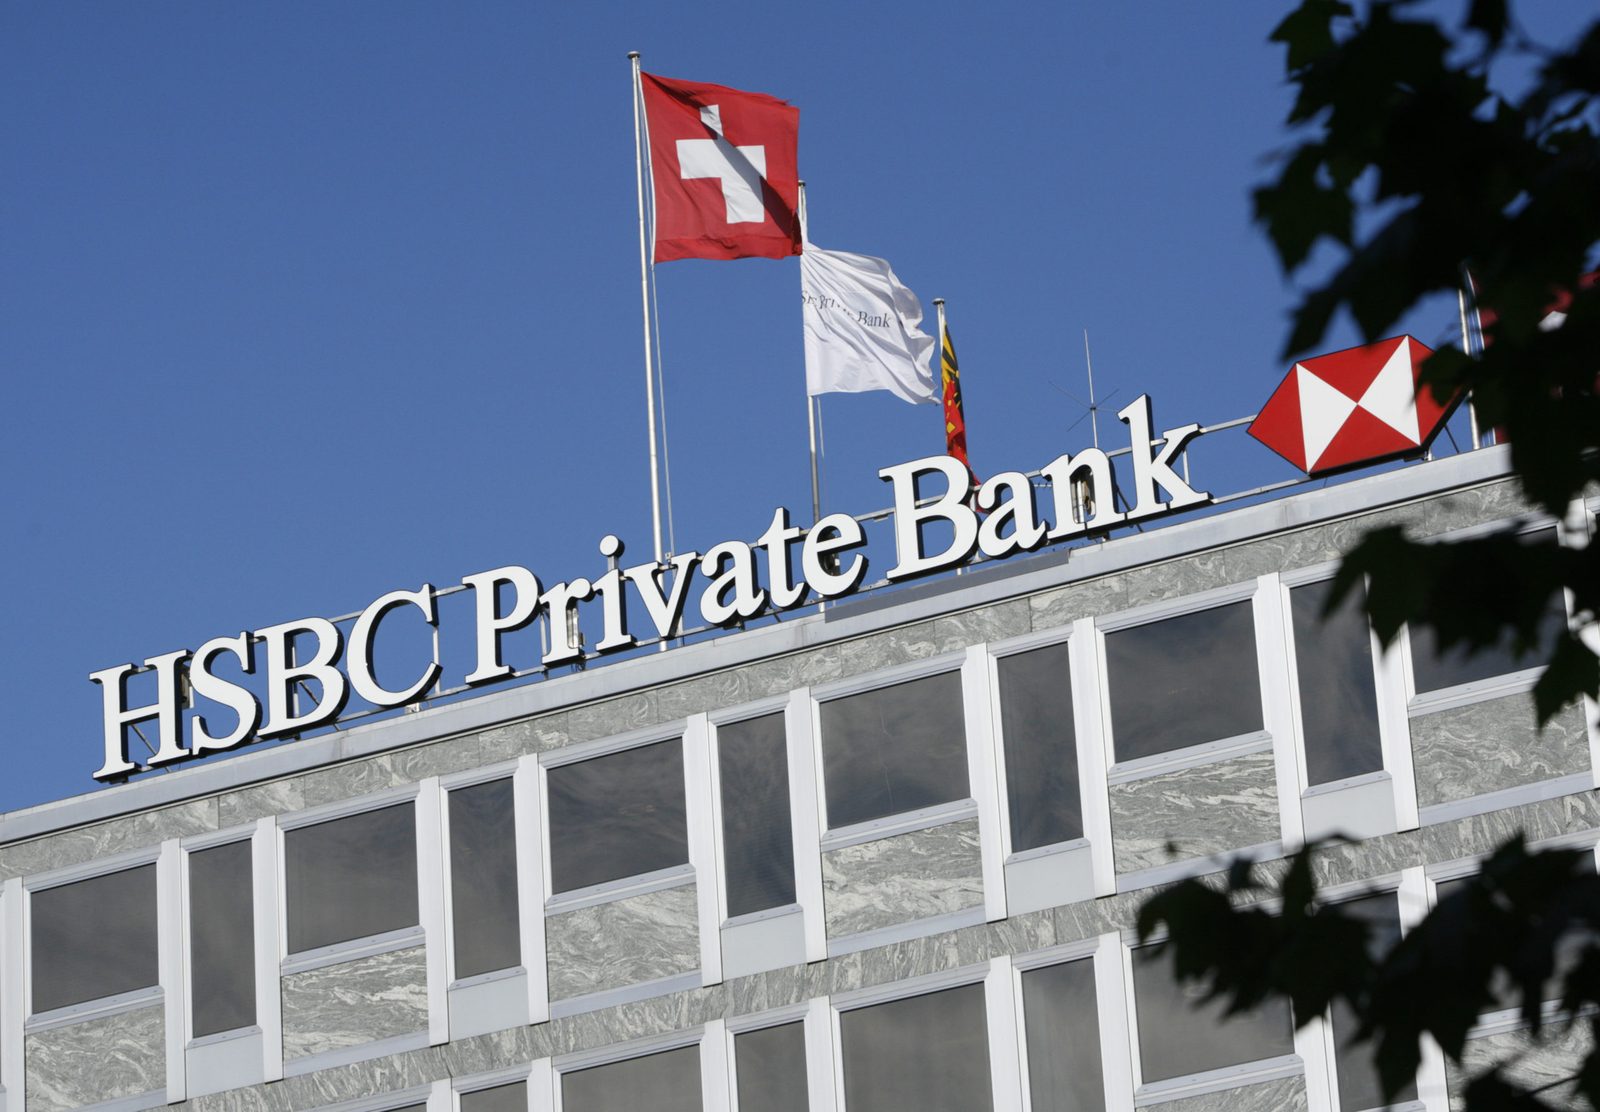
HSBC's private banking operations terminated relationships with over 1,000 high-net-worth clients across Middle Eastern markets. This action followed regulatory scrutiny regarding client risk management and compliance with anti-money laundering standards, though the institution maintains its commitment to broader regional operations.
Healthcare
Eli Lilly implemented substantial price increases for its diabetes medication in the UK private market, elevating costs by approximately 170 percent for higher-dosage formulations. Concurrently, Novo Nordisk launched discounted direct-payment programs in the United States for comparable treatments, reflecting divergent pricing strategies between competitors.
Industrials
Toyota Motor Corporation substantially reduced its profit expectations for the fiscal year, projecting a $9.5 billion impact from American tariffs on imported vehicles. The automaker revised annual operating profit guidance downward by 16 percent, though it reported record global sales during the first half of the period, driven primarily by hybrid vehicle demand.
Technology and Network Equipment
The U.S. government acquired approximately 9.9 percent equity ownership in Intel Corporation through a transaction valued near $11.1 billion. This investment converts previous grant allocations under semiconductor policy initiatives into direct shareholder participation, positioning the government as a principal stakeholder.
The Stock of the Month
Circle experienced significant valuation deterioration following its initial public offering period. The security's value decreased 29 percent throughout August and remains substantially below its June intraday peak. This normalization reflects investor reassessment following a secondary share offering and financial results disclosure.
Key Performance Metrics (as of August 31, 2025)
| Index/Asset | Value | Monthly Change | Year-to-Date |
|---|---|---|---|
| S&P 500 | 6460.26 | +1.53% | +9.84% |
| Dow Jones | 45544.88 | +2.44% | +7.05% |
| NASDAQ | 21455.55 | +1.54% | +11.11% |
| FTSE 100 | 9187.34 | +0.55% | +11.23% |
| CAC 40 | 7703.90 | -2.01% | +4.19% |
| DAX | 23902.21 | -1.48% | +19.36% |
| SMI 20 | 12187.58 | +2.14% | +4.85% |
| MSCI World | 4177.72 | +2.49% | +12.67% |
| VIX | 15.36 | -3.88% | -11.47% |
| CHF/USD | 1.2486 | +1.71% | +13.40% |
| CHF/EUR | 1.0684 | -0.62% | +0.39% |
| Brent Crude | $67.38/bbl | -6.08% | -9.90% |
| Gold | $3516.10/oz | +5.80% | +34.92% |
Upcoming Events
- September 8: French Government Confidence Vote
- September 11: ECB Governing Council Meeting
- September 16-17: FOMC Meeting